

WINGX Global Market Tracker:
Global business jet growth slows to 0.4% in Week 41
as charter demand softens
Global bizjet activity rose just 0.4% year-on-year in Week 41 (5-11 Oct), with just over 81,400 departures operated globally.
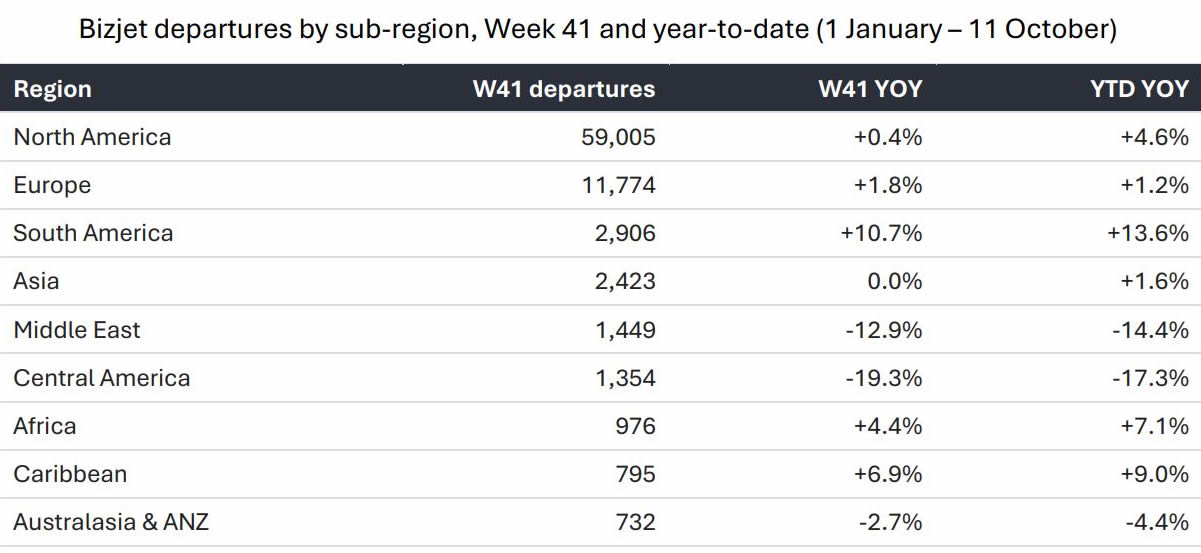
This was the slowest weekly growth since the Labor Day timing shift pulled Week 36 negative, and the four-week trend has eased to +2.3%. The year-to-date figure stands at +3.3% ahead of last year through 11 October. North America matched the global trend at +0.4%, Europe grew 1.8% and South America posted the strongest gain among the larger regions, up 10.7%. Central America (-19.3%) and the Middle East (-12.9%) remained the weakest sub-regions.
What Drove the Week
Unlike Week 40, when North America supplied almost all of the growth, gains in Week 41 were small and spread across several regions. South America added +0.35 points and North America +0.32 points, with Europe contributing +0.26 points. Central America (-0.40 points) and the Middle East (-0.27 points) took back most of those gains.
Contribution* to global bizjet departures YOY growth by sub-region (Week 41 2026 vs Week 41 2025).
click image to enlarge
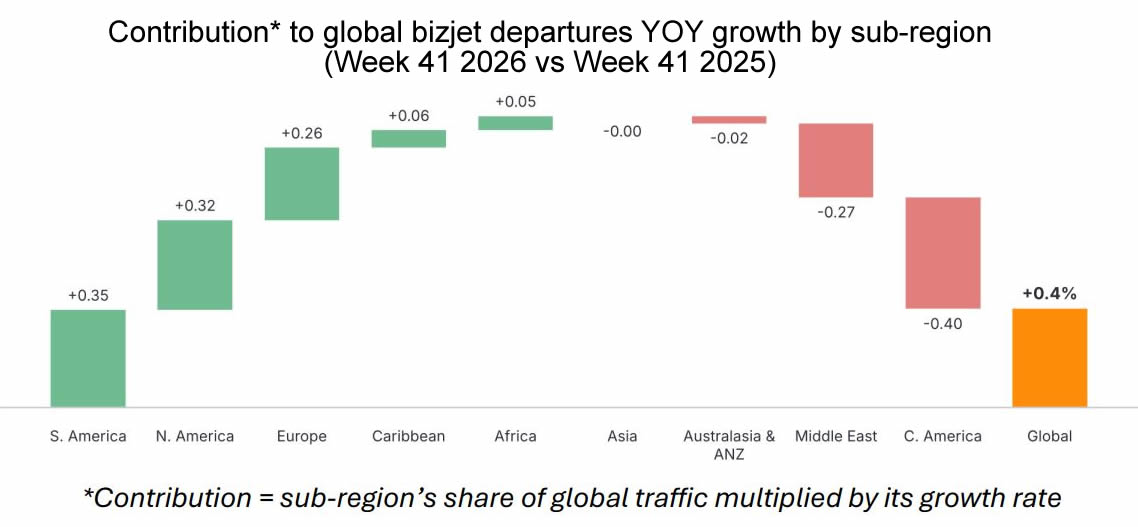
*Contribution = sub-region’s share of global traffic multiplied by its growth rate
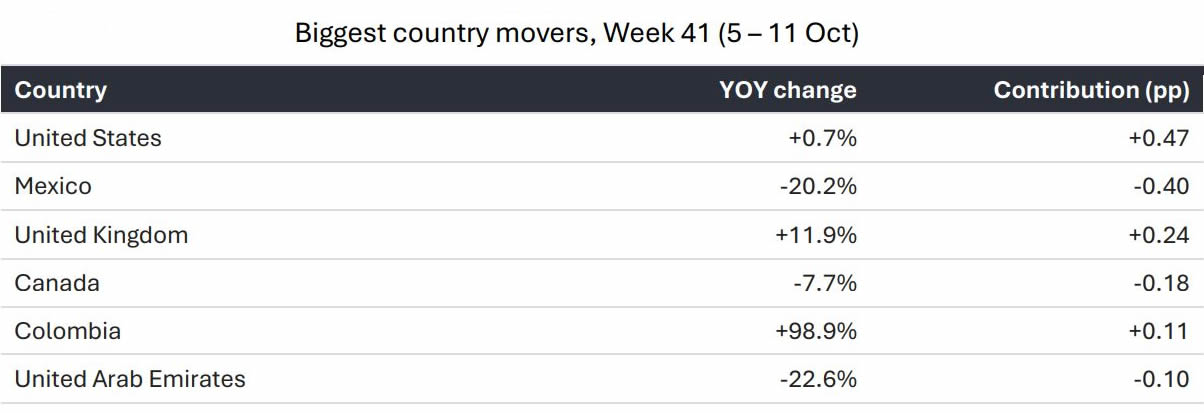
Growth rates alone can overstate smaller markets, so the table below ranks the week’s biggest country movers by their contribution to global growth. The United States, up just 0.7%, was still the largest single contributor, while Mexico’s 20.2% decline was again the largest drag. The UK stood out in Europe, up 11.9%.
Biggest country movers, Week 41 (5-11 Oct).
click image to enlarge
Trend Context
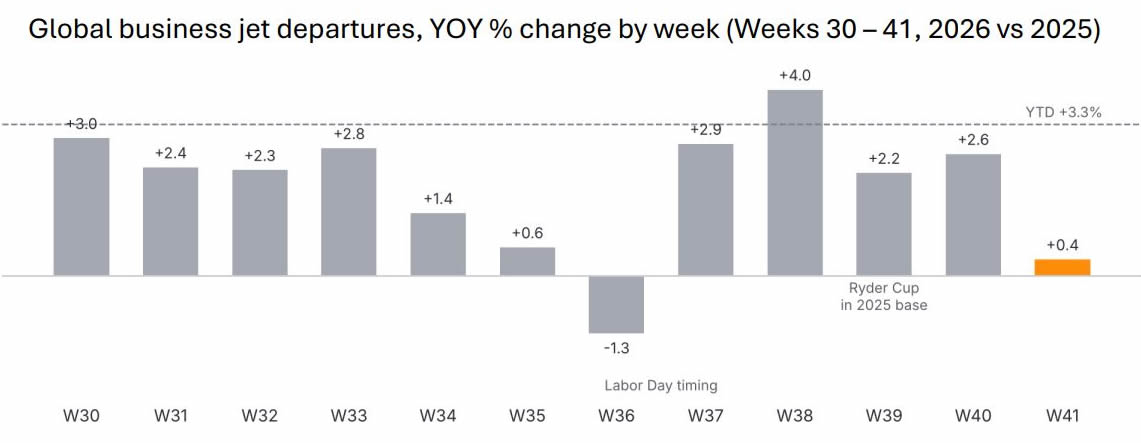
The chart below puts Week 41 in context. Weekly year-on-year growth held largely in a 2–4% range through the summer and early autumn, so a +0.4% week stands out. Much of the slowdown reflects last year’s comparison rather than a sudden drop in activity: Week 41 2026 was 2.3% busier than Week 40, a normal seasonal step, while Week 41 2025 jumped 4.6%,
marking the start of last year’s strong fourth quarter.
Global business jet departures, YOY % change by week (Weeks 30-41, 2026 vs 2025).
click image to enlarge
Midweek activity held up, with Monday up 2.7% and Tuesday up 3.9%, but the weekend was soft for a second week running: Saturday fell 2.8% and Sunday 4.9%, leaving Friday to Sunday down 2.2% against +2.1% from Monday to Thursday. The four-week trend of +2.3% now sits a full point below the year-to-date +3.3%.
Regional Performance Analysis in Week 41
Bizjet departures by sub-region, Week 41 and year-to-date (1 January-11 October).
click image to enlarge
North America
The North American market was close to flat last week, with demand up 0.4% year-on-year and just over 59,000 departures. The United States accounted for roughly 97% of North American flights (and around 70% of all global departures) with nearly 57,200 flights, up just 0.7%, while Canada fell 7.7%. The largest states were soft: Florida slipped 2.1%, California 2.5% and Tennessee 7.8%, with Texas flat. Growth instead came from the Northeast and mid-Atlantic, with New Jersey up 8.1% (Teterboro +4.5%), Pennsylvania +9.6% and North Carolina +7.6%. On a year-to-date basis, North America remains the anchor of global growth, up 4.6%.
Europe
European business jet traffic grew 1.8% year-on-year in Week 41 with just under 11,800 flights, and its year-to-date trend now sits at +1.2%. The UK did most of the work, up 11.9%, with three of the London business airports of Luton, Farnborough and Biggin Hill up 6.0% combined. Spain rose 3.7% and Italy 0.9%. In contrast, Germany fell 5.5%, Switzerland 1.8% and France 1.1%.
Rest of the World
Regions outside Europe and North America again moved in different directions. South America was the standout, up 10.7%, with broad gains outside Brazil: Colombia nearly doubled (+99%), Venezuela rose 42% and Argentina 16%, while Brazil added 2.3%. The Caribbean grew 6.9% and Africa 4.4%, while Asia was flat and Australasia & ANZ slipped 2.7%.
In the Middle East, Gulf departures from the UAE, Saudi Arabia, Qatar, Bahrain, Kuwait and Oman reached 552, their highest weekly total since February. However, last year’s October ramp-up was steeper, so the gap to 2025 widened to -27.7%, from -22.2% in Week 40. Turkey, the region’s largest market, was flat.
Mexico fell 20.2%, with flights by US-registered jets down 30.5% and Mexican-registered jets down 9.5%. Toluca fell 29%. Los Cabos bounced back after a weak Week 40, with its two airports handling 110 departures, up 24% on the same week last year.
Mover of the Week to Watch: Charter
Branded charter departures fell 10.2% year-on-year in Week 41, to 12,479 flights. This was the third consecutive weekly decline, following -1.6% in Week 39 and -4.6% in Week 40, and the steepest fall since at least July. Charter flew almost exactly as many flights as in Week 40, but last year’s Week 41 was 6% busier than the week before, and this year charter did not follow that seasonal lift.
Branded charter business jet departures, YOY % change by week (Weeks 30-41, 2026 vs 2025).
click image to enlarge
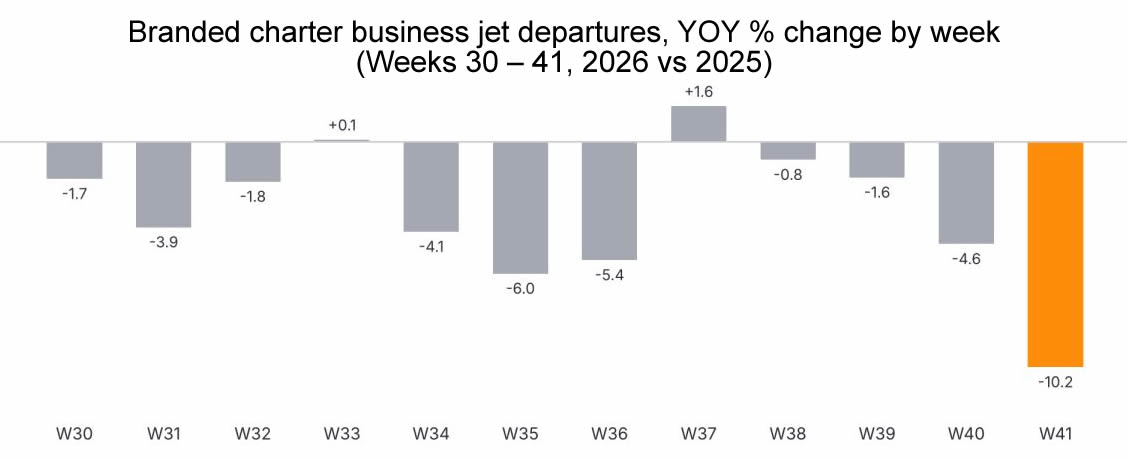
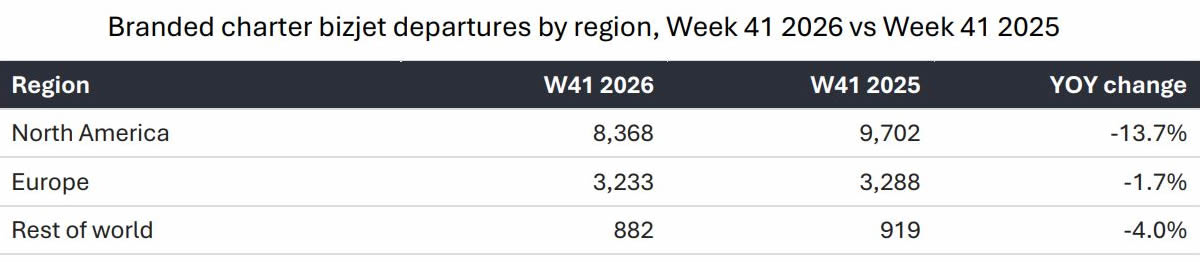
The decline is concentrated in North America, where branded charter fell 13.7%. In Europe the segment was only slightly down, at -1.7%. Year-to-date, branded charter is down 3.1%, the weakest of the main commercial operator types.
Branded charter bizjet departures by region, Week 41 2026 vs Week 41 2025.
click image to enlarge
Who Is Flying
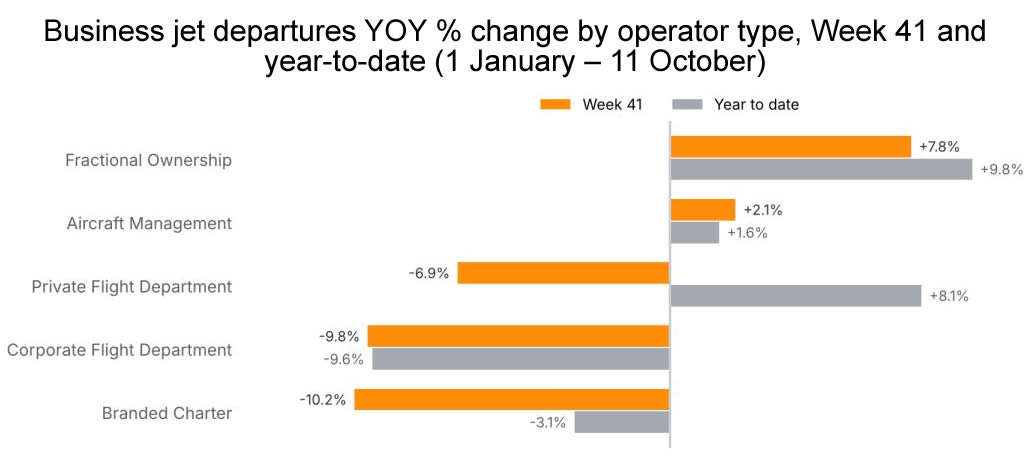
Fractional operators continued to grow, up 7.8% on the week and adding around 1.5 percentage points to global growth. Year-to-date, fractional activity is up 9.8%, and aircraft management edged up 2.1% on the week. In contrast, private flight departments fell 6.9%, although they remain up 8.1% year-to-date, and corporate flight departments fell 9.8%.
Business jet departures YOY % change by operator type, Week 41 and year-to-date (1 January-11 October).
click image to enlarge
Fleet Lens
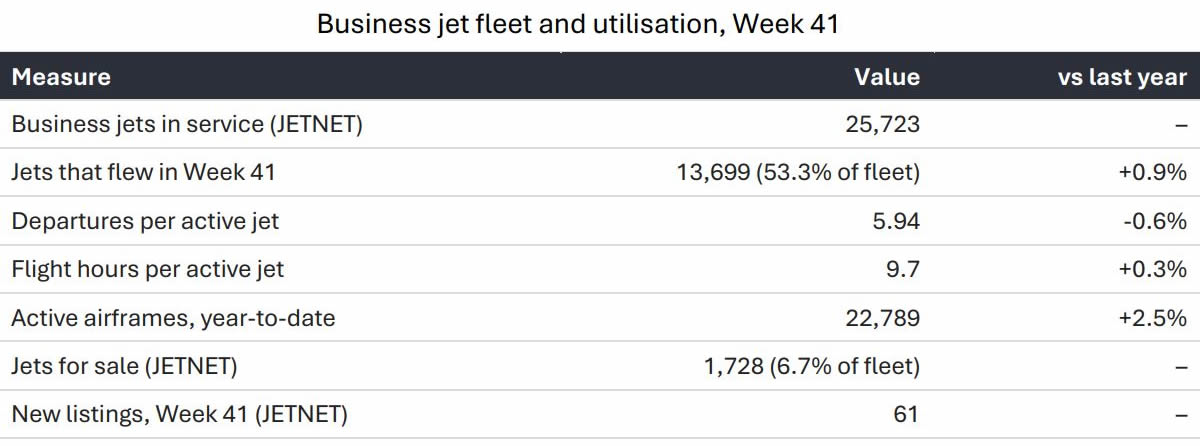
Combining WINGX flight data with JETNET fleet records shows that utilisation stalled in Week 41. The number of active jets rose 0.9%, but departures per active jet slipped 0.6% and flight hours per jet were essentially flat at +0.3%, a reversal of Week 40’s pattern of each aircraft flying more.
Business jet fleet and utilisation, Week 41.
click image to enlarge
Looking Ahead to Week 42
- Charter: a fourth consecutive weekly decline would make this the clearest soft patch in branded charter this year.
- Weekend activity: Friday to Sunday has now been soft for two weeks running; a third could point to cooling leisure demand.
- NBAA-BACE: last year’s show in Las Vegas fell in Week 42, lifting departures from the city’s airports to around 1,295 that week; if this year’s show falls in a different week, the comparison there will be demanding.
- Fourth quarter: last year’s surge began in Week 41, so year-on-year comparisons stay tough through November (+9.4% in November 2025).
Conclusion
Nick Koscinski, WINGX Analyst, comments, “Growth all but stalled last week at +0.4%, but I’m seeing that as last year’s Q4 surge kicking in rather than a sudden drop in demand.
"What we’re watching right now is the charter market, which is now down three weeks running and fell 10% last week, with North America hit hardest.
"Fractional is still growing nicely, so this looks like a squeeze on the more price-sensitive end of the market rather than a broad pullback.”
Note: Figures cover business jets including VIP/bizliner aircraft. All figures exclude turboprops.
This bulletin is produced by WINGX, part of the JETNET Group. The JETNET Group is an independent organisation with no commercial affiliation with BlueSky News. All references to products, services, and events in this bulletin are editorial in nature and have not been paid for or sponsored by any third party.
“Growth all but stalled last week at +0.4%, but I’m seeing that as last year’s Q4 surge kicking in rather than a sudden drop in demand.
"What we’re watching right now is the charter market, which is now down three weeks running and fell 10% last week, with North America hit hardest.
"Fractional is still growing nicely, so this looks like a squeeze on the more price-sensitive end of the market rather than a broad pullback.”
Nick Koscinski
WINGX Analyst.
WINGX GmbH
Lilienstraße 11
20095 Hamburg
Germany.
+49 40 23 96 85 05
BlueSky Business Aviation News | 15th October 2026 | Issue #862
| © BlueSky Business Aviation News Ltd 2008-2026 |